What is the Japan Data Center Rack Market Size?
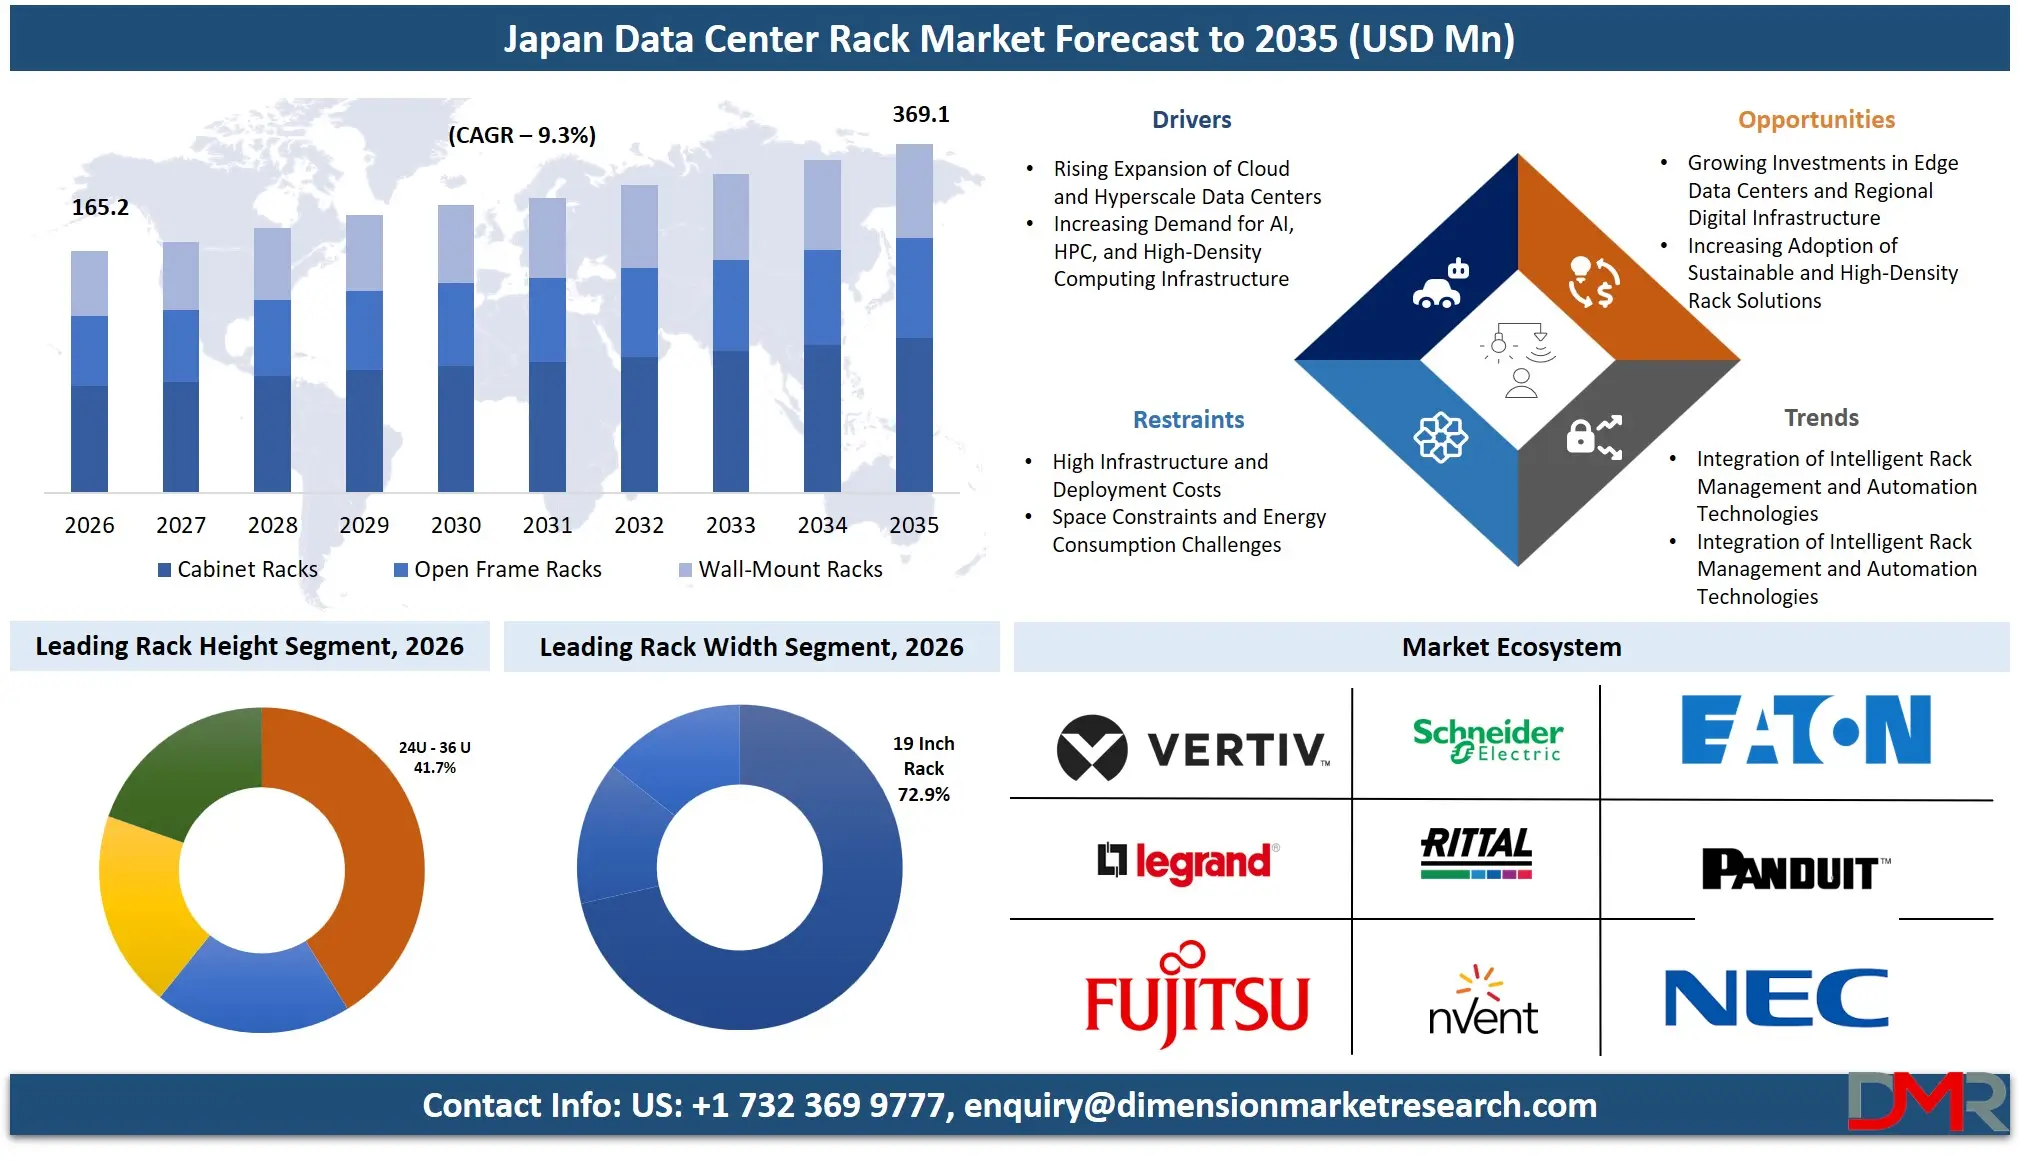
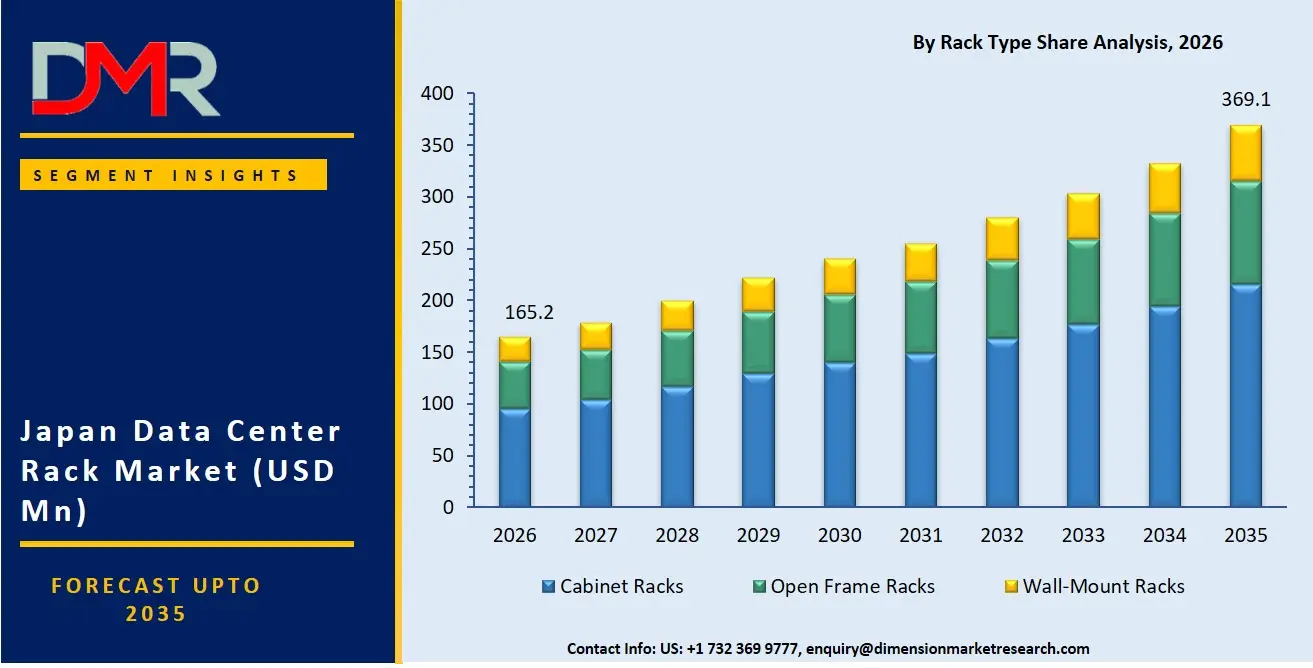
The Japan Data Center Rack Market size is expected to be USD 165.2 million in 2026 and increase at a compound annual growth rate of 9.3% to USD 369.1 million in 2035 owing to rising expansion of cloud and hyperscale data centers.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
The Japan Data Center Rack Market is witnessing steady expansion owing to increasing investments in hyperscale and colocation data centers, widespread cloud adoption, rapid digital transformation, and the growing deployment of artificial intelligence and high-performance computing infrastructure. Rising demand for secure, scalable, and energy-efficient server environments is encouraging organizations to upgrade rack systems with enhanced cooling compatibility and cable management capabilities. Government initiatives supporting digital infrastructure modernization, alongside increasing enterprise workloads and edge computing deployments, continue to strengthen market demand. Furthermore, sustainability goals and the adoption of modular data center designs are driving innovation in rack configurations, supporting long-term market growth across Japan.
Key Takeaways
- Market Size & Forecast: The Japan Data Center Rack Market size is projected to reach USD 165.2 million in 2026 and is anticipated to have a value of USD 369.1 million in 2035.
- Growth Rate & Outlook: The Japan Data Center Rack Market size is set to grow at a compound annual growth rate of 9.3% during the forecast period of 2026 to 2035.
- Primary Growth Drivers: Some of the major growth drivers in the market are Rising Expansion of Cloud and Hyperscale Data Centers, and more.
- Key Market Trends: Some of the major trends in the market are Rising Adoption of Modular and Liquid Cooling-Compatible Rack Designs and more.
- By Rack Height: The 24U–36U segment is expected to hold the largest revenue share of 41.7% in the Japan Data Center Rack Market in 2026.
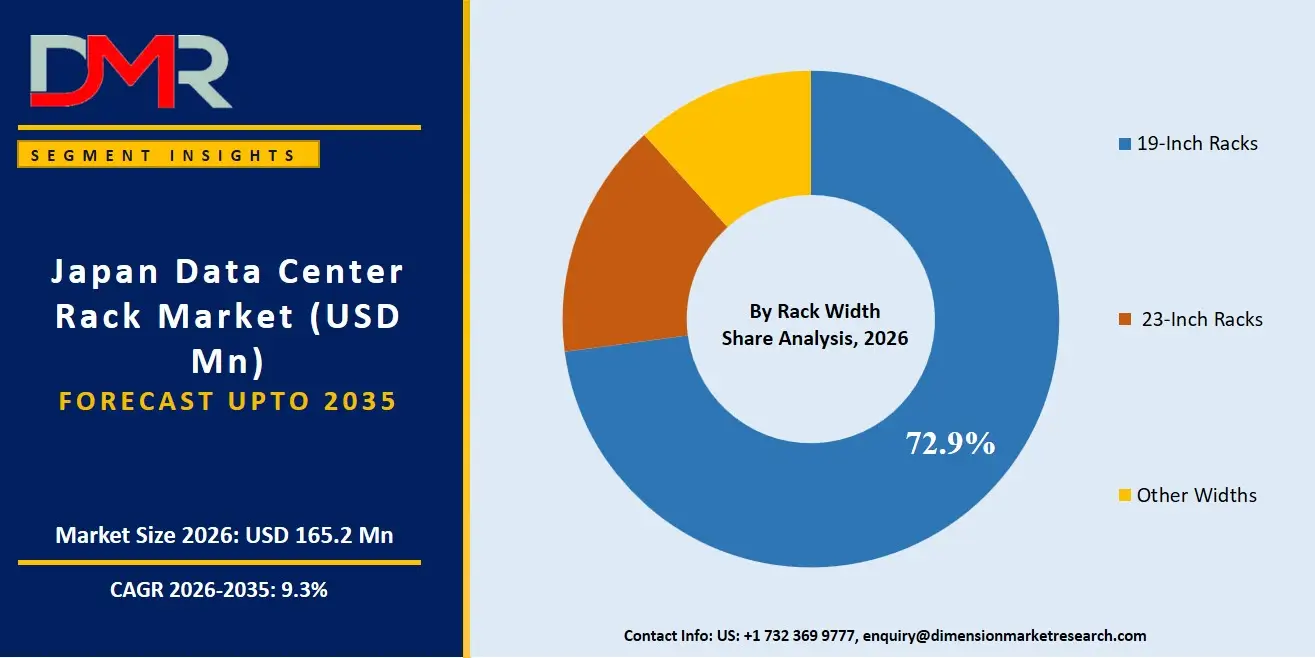
- By Rack Width: The 19-Inch Racks segment is expected to dominate the Japan Data Center Rack Market with a revenue share of 72.9% in 2026.
- By End User: Cloud Service Providers are projected to lead the Japan Data Center Rack Market with a revenue share of 46.3% in 2026, driven by cloud migration, hyperscale infrastructure expansion, and increasing AI workloads.
- By Industry Vertical: IT & Telecommunications is expected to dominate the Japan Data Center Rack Market with a revenue share of 33.8% in 2026, supported by expanding 5G networks, cloud integration, and increasing data traffic.
What is the Data Center Rack?
A data center rack is a standardized physical framework designed to securely house, organize, and support servers, storage systems, networking equipment, power distribution units, and other IT hardware within a data center. Typically manufactured in standardized dimensions such as 19-inch or 23-inch widths and measured in rack units (U), these racks facilitate efficient equipment installation, airflow management, cable organization, and maintenance accessibility. Available in cabinet, open-frame, and wall-mount configurations, data center racks enhance equipment protection, optimize space utilization, improve cooling efficiency, and enable scalable infrastructure deployment for modern computing environments.
Use Cases
- Hyperscale Cloud Data Centers: Data center racks are extensively deployed in hyperscale cloud facilities to accommodate high-density servers, storage systems, and networking equipment. Their modular design supports scalability, efficient airflow, and organized cable management, enabling cloud providers to expand computing capacity while maintaining operational efficiency and reducing infrastructure downtime.
- Colocation Data Centers: Colocation operators utilize standardized rack solutions to securely host IT equipment for multiple customers within shared facilities. Advanced rack configurations with integrated locking systems, power distribution, and cable management improve equipment security, simplify maintenance, and maximize floor space utilization while meeting varying customer infrastructure requirements.
- Enterprise IT Infrastructure: Large enterprises across sectors such as banking, manufacturing, healthcare, and retail deploy data center racks to centralize servers and networking hardware. These racks facilitate structured equipment organization, simplify system upgrades, improve cooling performance, and support business continuity through reliable infrastructure management.
- Edge Computing Facilities: As edge computing expands across Japan, compact and high-performance data center racks are increasingly installed in distributed facilities closer to end users. These racks support low-latency applications, industrial automation, IoT deployments, and AI-enabled workloads while enabling efficient use of limited installation space and simplified remote infrastructure management.
How AI Is Transforming the Japan Data Center Rack Market
Artificial intelligence is transforming the Japan Data Center Rack Market by improving infrastructure monitoring, predictive maintenance, and energy optimization. AI-powered analytics continuously monitor rack temperature, airflow, power consumption, and equipment performance, enabling operators to identify potential failures before they disrupt operations. This improves infrastructure reliability while reducing maintenance costs and unplanned downtime.
AI is also driving demand for next-generation rack systems capable of supporting GPU-intensive computing environments and advanced cooling technologies. Intelligent rack management platforms optimize equipment placement, automate workload distribution, enhance thermal efficiency, and improve overall resource utilization. As AI workloads continue to expand across cloud, enterprise, and research facilities, rack manufacturers are developing higher-density, scalable, and automation-ready solutions to meet evolving infrastructure requirements.
Market Dynamic
Driving Factors in the Japan Data Center Rack Market
Rising Expansion of Cloud and Hyperscale Data Centers
The continuous expansion of cloud computing services and hyperscale data center investments is a major driver of the Japan Data Center Rack Market. Increasing enterprise migration toward cloud platforms has created substantial demand for high-density rack systems capable of supporting advanced computing infrastructure. Hyperscale facilities require standardized, scalable, and energy-efficient rack solutions that can accommodate growing server deployments while ensuring effective thermal management and cable organization. As digital transformation accelerates across industries, demand for modern rack infrastructure continues to strengthen throughout Japan.
Growing Demand for AI-Ready and High-Density Rack Infrastructure
The increasing adoption of artificial intelligence, high-performance computing, and advanced data processing technologies is driving demand for high-density data center rack systems across Japan. AI servers and GPU-intensive computing infrastructure require specialized racks capable of supporting higher equipment loads, advanced cooling arrangements, and efficient power distribution. Organizations are upgrading conventional rack installations to accommodate greater computing capacity while improving operational reliability. Rising investment in AI-ready data centers, particularly among cloud service providers and colocation operators, is supporting the adoption of advanced rack solutions with enhanced structural strength, thermal management compatibility, and scalability.
Restraints in the Japan Data Center Rack Market
Space Constraints and Increasing Power Density Requirements
Limited available space in major Japanese metropolitan areas and increasing power density requirements present challenges for data center rack deployments. Facilities supporting artificial intelligence and high-performance computing require racks capable of accommodating heavier equipment, advanced cooling systems, and complex power distribution arrangements. Retrofitting existing data centers to support these requirements can involve structural modifications, additional cooling investments, and extended installation timelines. These constraints may increase infrastructure costs and complicate capacity expansion, particularly for older facilities operating in densely developed urban locations.
High Infrastructure and Deployment Costs
Deploying advanced data center rack systems requires considerable investment in supporting infrastructure, including cooling systems, power distribution, cable management, and physical security. High-density racks designed for AI and hyperscale environments often involve additional installation and maintenance expenses. These capital-intensive requirements can discourage smaller enterprises and regional operators from upgrading existing facilities, thereby limiting broader market adoption despite growing digital infrastructure demand.
Opportunities in the Japan Data Center Rack Market
Increasing Adoption of Liquid Cooling-Compatible Rack Systems
The growing deployment of high-performance computing infrastructure and AI servers presents opportunities for manufacturers offering liquid cooling-compatible data center racks. Increasing computing density requires improved thermal management beyond conventional air-cooling systems, encouraging operators to explore direct-to-chip cooling, rear-door heat exchangers, and hybrid cooling architectures. Rack manufacturers can capitalize on these requirements by developing modular enclosures with integrated coolant distribution support, enhanced load capacities, and improved cable management. Partnerships with cooling equipment providers and data center operators may further support the commercialization of advanced rack solutions across Japan.
Growing Investments in Edge Data Centers and Regional Digital Infrastructure
The expansion of edge computing infrastructure across Japan presents significant opportunities for data center rack manufacturers and solution providers. Increasing deployment of localized data centers to support 5G networks, smart manufacturing, autonomous technologies, and Internet of Things (IoT) applications is creating demand for compact, modular, and highly efficient rack systems. Organizations are seeking flexible rack solutions that can be rapidly deployed in distributed environments while maintaining high reliability, simplified maintenance, and optimized cooling performance. This trend is expected to broaden the addressable market beyond traditional hyperscale facilities.
Trends in the Japan Data Center Rack Market
Increasing Focus on Seismic-Resistant and Energy-Efficient Rack Systems
Data center operators in Japan are increasingly emphasizing rack infrastructure designed to improve seismic resilience, operational safety, and energy efficiency. The country's exposure to earthquakes creates a need for stable rack structures, reinforced mounting systems, and secure equipment installations. At the same time, sustainability objectives are encouraging the adoption of rack configurations that optimize airflow, reduce cooling inefficiencies, and improve equipment organization. Manufacturers are responding through innovations in structural design, modular construction, and thermal management compatibility, supporting more reliable and efficient data center operations..
Rising Adoption of Modular and Liquid Cooling-Compatible Rack Designs
The growing deployment of AI servers and high-performance computing infrastructure is accelerating demand for modular rack designs compatible with advanced cooling technologies. Operators are increasingly selecting rack systems that support liquid cooling, rear-door heat exchangers, and higher power densities to efficiently manage thermal loads. Modular architectures also simplify future capacity expansion, enabling organizations to respond quickly to changing computing requirements while improving energy efficiency and optimizing valuable data center floor space.
Research Scope and Analysis
The research scope of the Japan Data Center Rack Market covers detailed segmentation across rack type, rack height, rack width, end user, and industry vertical, analyzing demand patterns and adoption trends. It evaluates technological advancements, including high-density and AI-ready rack systems, and their impact on infrastructure efficiency. The analysis highlights market dynamics, competitive strategies, and growth drivers. It also assesses 2026 segment share estimates, identifying leading and fastest-growing categories across enterprise, cloud, and colocation deployments.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
By Rack Type Analysis
The Japan Data Center Rack Market by rack type is segmented into cabinet racks, open frame racks, and wall-mount racks. Cabinet racks dominate the market with an estimated 58.4% share in 2026, driven by their strong adoption in hyperscale and colocation data centers due to superior security, cooling efficiency, and structured cable management.
ℹ
To learn more about this report –
Download Your Free Sample Report Here
These racks are widely preferred for mission-critical workloads and high-density server environments. Open frame racks are witnessing steady demand in enterprise and lab environments where accessibility and cost efficiency are prioritized. Meanwhile, wall-mount racks are gaining traction in edge computing and small IT setups due to compact design and space optimization needs, making them the fastest-growing sub-segment.
By Rack Height Analysis
The market is segmented into below 24U, 24U–36U, 37U–48U, and above 48U. The 24U–36U segment holds the leading share at 41.7% in 2026, supported by balanced capacity and flexibility for enterprise and colocation deployments. These racks offer optimal space utilization while accommodating moderate-to-high server density requirements. The above 48U segment is expanding rapidly due to hyperscale data center expansion and AI workload adoption, which require high-density rack infrastructure. Smaller racks below 24U continue to serve edge computing and distributed IT environments, particularly in retail and telecom installations.
By Rack Width Analysis
By rack width, the market includes 19-inch racks, 23-inch racks, and other widths. The 19-inch rack segment dominates with an estimated 72.9% share in 2026, owing to its global standardization and widespread compatibility with servers, switches, and storage systems. Its dominance is reinforced by strong adoption across cloud providers, enterprises, and colocation facilities. The 23-inch segment is gradually expanding, particularly in telecommunications and specialized infrastructure deployments requiring higher equipment density. Other widths remain niche but are used in customized industrial applications.
By End User Analysis
The end user segmentation includes colocation providers, cloud service providers, enterprises, and government organizations. Cloud service providers hold the leading share at 46.3% in 2026, driven by rapid cloud migration, AI workload growth, and hyperscale infrastructure expansion across Japan. Colocation providers are also experiencing strong demand due to increasing outsourcing of IT infrastructure. Enterprises are steadily modernizing legacy data centers, while government organizations are investing in secure and resilient digital infrastructure for public services and defense applications.
By Industry Vertical Analysis
Key industry verticals include IT & telecommunications, BFSI, healthcare, government & defense, manufacturing, retail & e-commerce, energy & utilities, media & entertainment, and others. The IT & telecommunications segment leads with 33.8% share in 2026, supported by 5G expansion, cloud integration, and increasing data traffic. BFSI is another major contributor due to secure transaction processing needs and regulatory compliance requirements. Healthcare and government sectors are growing steadily with digitalization and data security initiatives, while manufacturing is emerging strongly with Industry 4.0 and smart factory adoption.
The Japan Data Center Rack Market Report is segmented on the basis of the following:
By Rack Type
- Cabinet Racks
- Open Frame Racks
- Wall-Mount Racks
By Rack Height
- Below 24U
- 24U–36U
- 37U–48U
- Above 48U
By Rack Width
- 19-Inch Racks
- 23-Inch Racks
- Other Widths
By End User
- Colocation Providers
- Cloud Service Providers
- Enterprises
- Government Organizations
By Industry Vertical
- IT & Telecommunications
- BFSI
- Healthcare
- Government & Defense
- Manufacturing
- Retail & E-commerce
- Energy & Utilities
- Media & Entertainment
- Other Industries
Competitive Landscape
The Japan Data Center Rack Market is characterized by strong competition driven by innovation, customization, and energy efficiency improvements. Market participants are focusing on developing high-density, modular, and AI-compatible rack solutions to meet the evolving requirements of hyperscale and edge data centers. Strategic emphasis is placed on enhancing thermal management capabilities, supporting liquid cooling integration, and improving structural flexibility for scalable deployments. Companies are also investing in advanced materials, smart rack monitoring systems, and sustainable manufacturing practices. Partnerships with cloud providers, colocation operators, and telecom firms are increasingly shaping competitive positioning, while high entry barriers exist due to technical complexity, certification standards, and infrastructure integration requirements.
Some of the prominent players in the Japan Data Center Rack are:
- Nitto Kogyo Corporation
- Kawamura Electric Industrial Co., Ltd.
- Settsu Metal Industrial Co., Ltd.
- Sanwa Supply Inc.
- Takachi Electronics Enclosure Co., Ltd.
- Schneider Electric SE
- Vertiv Holdings Co.
- Rittal GmbH & Co. KG
- Legrand SA
- Eaton Corporation plc
- Panduit Corporation
- nVent Electric plc
- Chatsworth Products, Inc.
- Tripp Lite (Eaton)
- Huawei Technologies Co., Ltd.
- Other Key Players
Recent Developments
- In June 2026, Vertiv introduced its Rack Extreme platform, designed to support high-density computing and artificial intelligence infrastructure. The next-generation rack system features higher equipment load capacities, deeper configurations, and improved cable management, supporting the evolving requirements of AI-enabled data centers.
- In October 2025, Vertiv announced its SmartIT OCP rack solution as part of a broader portfolio of rack, power, and cooling technologies aligned with Open Compute Project guidelines. The configurable rack system is designed to support high-density computing infrastructure and simplify equipment integration for modern data center environments.
- In June 2025, Schneider Electric announced new AI-focused data center infrastructure solutions, including NetShelter SX Advanced enclosures and NetShelter Open Architecture rack systems. These solutions support high-density AI servers, reinforced equipment loading, improved power distribution, and liquid cooling integration for next-generation computing facilities.
Report Details
| Report Characteristics |
| Market Size (2026) |
USD 165.2 Mn |
| Forecast Value (2035) |
USD 369.1 Mn |
| CAGR (2026–2035) |
9.3% |
| Historical Period |
2021 – 2025 |
| Forecast Period |
2027 – 2035 |
| Base Year |
2025 |
| Estimate Year |
2026 |
| Segments Covered |
By Rack Type, By Rack Height, By Rack Width, By End User, By Industry Vertical |
Frequently Asked Questions
How big is the Japan Data Center Rack Market?
▾ The Japan Data Center Rack Market size is expected to reach USD 165.2 million by 2026 and is projected to reach USD 369.1 million by the end of 2035.
What is the CAGR of the Japan Data Center Rack Market from 2026 to 2035?
▾ The market is growing at a CAGR of 9.3 percent over the forecasted period.
What factors are driving the growth of the Japan Data Center Rack Market?
▾ Rising Expansion of Cloud and Hyperscale Data Centers, and more are the factors driving the growth of the Japan Data Center Rack Market.
What are the major trends in the Japan Data Center Rack Market?
▾ Rising Adoption of Modular and Liquid Cooling-Compatible Rack Designs, and more are some of the major trends in the market.
Who are the key players in the Japan Data Center Rack Market?
▾ Some of the key players in the Japan Data Center Rack Market include Nitto Kogyo Corporation, Kawamura Electric Industrial Co., Ltd., Sanwa Supply Inc., Schneider Electric SE, Vertiv Holdings Co., Rittal GmbH & Co. KG, Eaton Corporation plc, and other prominent rack infrastructure providers.
How is the Japan Data Center Rack Market segmented?
▾ The Japan Data Center Rack Market is segmented by rack type, rack height, rack width, end user, industry vertical.